Real Estate Market: A Los Angeles Buyer and Seller Guide
The real estate market becomes easier to understand when you stop treating it as one national story. A headline about falling sales does not tell you whether a particular home is overpriced. A report about rising prices does not establish the value of your property. Your decision depends on the homes that compete with yours, the buyers who can afford them, and the financial terms available when you act.
For readers considering Los Angeles, Beverly Hills, or the San Fernando Valley, this guide offers a practical way to interpret those moving parts. Use it to organize your questions before a conversation with Rana Real Estate, rather than allowing a national prediction to make a personal financial decision for you.
What is the real estate market?
The real estate market is the interaction between properties offered for sale, people willing and able to buy them, and the prices and contract terms they negotiate. Supply, demand, financing, property condition, and location all matter. The most useful market analysis matches the location, property type, price range, and timing of your decision.
A market is not simply a collection of listing prices. Asking prices describe what sellers hope to receive. Closed sales show what completed transactions achieved. Pending contracts provide more recent evidence of activity, although their final prices may not yet be public.
The distinction matters because each measure answers a different question. Listings describe your alternatives today. Closings help establish historical support for a price. Pending activity helps reveal whether buyers are engaging with current inventory.
Your goal is not to discover one perfect number. It is to assemble enough relevant evidence to make a decision that remains sensible under more than one possible market outcome.
A dated Los Angeles market snapshot
The California Association of REALTORS' September 2026 county table reported a $994,670 median existing single-family home price for Los Angeles County, up 1.2% from September 2025. Reported county sales were 10.9% lower than a year earlier, though 5.4% higher than in August. These figures describe that reporting period and property category, not every neighborhood or type of home. [1]
For financing context, Freddie Mac reported a 7.40% national average for 30-year fixed mortgages on October 15, 2026. That average is not a personalized offer, and a local borrower’s quote can differ. [2]
These two observations should not be combined into a sweeping conclusion that every seller has leverage. Countywide prices can rise while certain buildings or price ranges become harder to sell. Likewise, higher sales activity does not establish that a specific home will receive multiple offers.
Treat this snapshot as background. Before making an offer or choosing a list price, request newer property-specific evidence and confirm the reporting dates. Monthly housing statistics and weekly mortgage information move on different schedules.
Why your local segment matters more than the headline
Start with the actual jurisdiction
“Los Angeles” can refer to the city, the county, or a much broader regional housing conversation. Those boundaries are not interchangeable. The City of Los Angeles' transfer-tax rules, for example, concern property within its jurisdiction, not automatically every home with a Los Angeles County address. [3]
Before comparing properties, identify the city and parcel. Then confirm which agencies handle building records, planning, taxation, and rental regulations. A mailing address or neighborhood label is not a substitute for this check.
Compare properties that compete for similar buyers
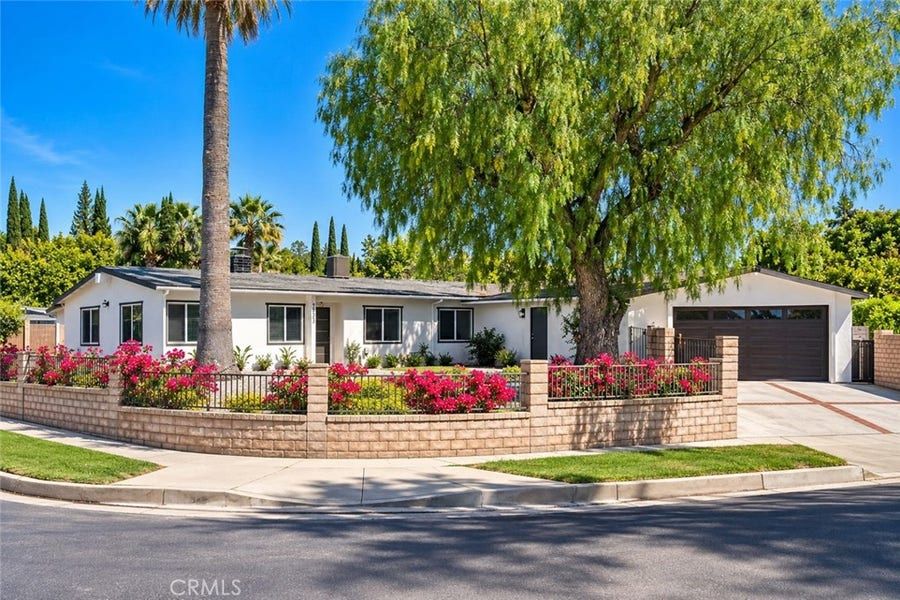
A useful comparison asks what a buyer would realistically choose instead. For a condominium, that may mean other units with similar fees, parking, building condition, and financing availability. For a detached home, lot usability, layout, repairs, and location may matter more than a small difference in interior square footage.
Do not stretch a comparison merely to justify a preferred result. A renovated property with a practical layout may not be a good match for an unrenovated home with awkward access. A large lot does not necessarily have equal value if much of it cannot serve the buyer’s intended use.
Separate price bands
Broad statistics can conceal different conditions at different budgets. In an illustrative neighborhood, homes under a particular payment threshold might attract several buyers while more expensive listings receive limited attention.
That is not a contradiction. It is a reason to define the competition carefully. Ask for evidence within a realistic price band before deciding whether an overall market label applies to your search.
Six signals that explain market conditions
1. Active inventory
Inventory is the collection of homes currently offered for sale. More choices can give buyers alternatives, but quantity alone does not establish quality.
Review how much of the inventory meets your actual requirements. Ten additional listings provide little practical benefit if none has the access, layout, or condition you need. Sellers should ask the same question in reverse: how many genuinely comparable alternatives compete for the buyer they hope to attract?
2. Months of supply
A simple months-of-supply calculation divides active listings by a stated monthly sales pace. If a hypothetical segment has 120 active listings and averages 20 completed sales per month, that calculation produces six months of supply.
The result depends on the dataset and method. A calculation using one month of sales can differ from one using a longer average. New listings, withdrawn properties, and changing demand will also affect what happens next.
Use months of supply as a directional indicator, not a countdown promising when a home will sell. Consistent methodology matters more than treating a single threshold as a universal law.
3. Time on market
Longer marketing periods can suggest that buyers have more time to compare options. But an average can hide a mix of quickly sold homes and stale listings.
Ask about the median, the range, and cumulative marketing history. Investigate whether a property was withdrawn and relisted. A newly displayed listing date may not tell the entire story.
Then ask why time accumulated. Access restrictions, unrealistic pricing, repair concerns, or an unusual layout can produce very different negotiating situations.
4. Price reductions
A price cut measures a change in the seller’s asking price, not necessarily a bargain. A home reduced from an unrealistic starting point may still be expensive relative to alternatives.
Follow reductions through to their outcome. Did showings improve? Did the property go under contract? Did it close? A reduction that creates buyer engagement provides more useful evidence than a dramatic percentage displayed without context.
5. Sale-to-list price
Always identify the denominator. Imagine a home originally listed at $1,050,000, reduced to $980,000, and sold for $960,000. It sold for about 98% of its final asking price but only about 91% of its original asking price.
Both statements are mathematically valid. They describe different aspects of the transaction. Asking which list price is being used helps prevent selective comparisons.
6. Pending and completed sales together
Pending contracts suggest current buyer activity, while completed sales provide confirmed outcomes. Reading them together is more useful than relying on either alone.
A cluster of new pending contracts may indicate stronger demand, but some transactions can still fail. A series of older closings may support valuation while lagging behind a recent financing change. The appropriate interpretation is cautious and specific, not automatic.
A median price is not your home’s valuation
The median is the middle price in a set of sales. If the mix of homes changes, the median can change even when comparable individual properties have not moved by the same percentage.
Consider three illustrative sales of $700,000, $900,000, and $1,100,000. Their median is $900,000. If the next period contains sales of $900,000, $1,100,000, and $1,500,000, the median becomes $1,100,000. That does not prove the original $900,000 home appreciated by $200,000.
A property-level valuation requires closer comparisons. The Consumer Financial Protection Bureau explains that appraisals, broker opinions, and automated models can differ because they use different information, comparisons, timing, or purposes. [4]
An online estimate can start a conversation. It should not end one. Ask which recent transactions support the estimate and which important property characteristics the model may not capture.
Affordability connects the market to your household
Two buyers can look at the same home and reach different reasonable conclusions. One may have stable income, substantial reserves, and a long ownership horizon. The other may expect a job change and need access to savings.
A lender’s approval is not a complete household budget. The CFPB recommends evaluating what you can repay comfortably alongside other expenses and savings priorities, rather than focusing only on the maximum available loan. [5]
Build an ownership budget that separates the mortgage from taxes, insurance, association charges, maintenance, and foreseeable projects. Then compare that budget with actual take-home income.
For an illustrative planning exercise, assume a household can comfortably allocate $6,000 each month to all housing-related costs. If verified nonmortgage costs total $1,500, only $4,500 remains for principal and interest. Starting with a $6,000 mortgage payment would misstate that household’s capacity.
The same principle applies to cash. Your down payment is only one use of funds. Closing expenses, moving, initial repairs, and an emergency reserve must fit into the plan without depending on immediate appreciation.
How buyers can use market information
First, define a comfortable payment and a maximum cash commitment before negotiating. These limits help keep an appealing listing from rewriting your financial priorities.
Second, request a comparison that includes sold homes, pending activity where available, and competing listings. Each category should be clearly labeled. Avoid treating an optimistic asking price as proof of value.
Third, study the property’s individual history. A long marketing period may create an opening, but it should prompt questions rather than assumptions about the seller’s finances or motivation.
Fourth, compare complete offer structures. A lower price, a permitted closing-cost credit, a repair agreement, and a flexible closing date affect the parties differently. The most useful concession depends on your actual constraint.
Finally, preserve an appropriate investigation process. A favorable market does not remove the need to understand property condition. An appraisal addresses valuation; an inspection investigates physical concerns. They serve different purposes. [6]
A strong purchase is not defined by winning every negotiating point. It is defined by obtaining a suitable property on understandable terms without accepting risks your budget cannot absorb.
How sellers can respond without chasing headlines
A seller should begin with the question a buyer will ask: why choose this home over the alternatives available today?
The answer combines pricing, presentation, condition, access, and confidence in the information supplied. Marketing cannot repair a major mismatch between asking price and competing value.
Build a pricing range from relevant evidence, then choose a launch strategy consistent with your timeline. A seller who needs a prompt move may make different tradeoffs from one who can remain comfortably in place.
Preparation should address the obstacles most likely to make buyers hesitate. That may mean explaining a flexible room layout, documenting completed work, improving photography, or making inspection information easier to review.
The National Association of REALTORS includes competitive pricing, photography, staging, showings, and other outreach within a home-marketing strategy. None of these elements should be considered in isolation. [7]
After launch, evaluate behavior rather than compliments. Strong online attention with few showings suggests a different problem from frequent showings without offers. The first may call for examining presentation or accessibility; the second may call for closer attention to price, condition, or expectations.
Do not assume every quiet week requires a price cut. Do not assume patience will solve every mismatch either. Agree on review points before emotions take over.
Local costs and records can change the decision
Property taxes after a purchase
The Los Angeles County Assessor explains that supplemental taxes can arise from the difference between a property’s previous assessment and its new assessment. These bills are separate from regular annual taxes and generally are not paid through an impound account. [8]
For planning, ask for an estimate based on the proposed purchase rather than copying the seller’s existing bill. A longstanding ownership history can make that old bill a poor guide to the buyer’s future obligation.
Insurance is part of property selection
The California Department of Insurance warns that comparison-tool premiums are based on hypothetical scenarios. An exact quote and eligibility determination require contact with an insurer, agent, or broker. [9]
Make insurance a property-specific question early in the process. Compare coverage, exclusions, deductibles, and replacement-cost assumptions, not just the annual premium. A home that fits the mortgage budget may still require a different insurance plan than expected.
Permits and legal use
A listing description is not a substitute for building records. LADBS provides resources for researching permits, inspections, and code-enforcement information within its jurisdiction. [10]
When a property’s value depends on an addition, conversion, or future development plan, investigate the records supporting that use. Attractive space and approved space are not always the same thing.
What the market means for investors
An owner-occupant may reasonably place substantial value on enjoying the home. An investor must also test whether the property’s business plan works.
Separate projected appreciation from operating performance. Ask what rent is supported, what expenses are documented, what work is required, and what financing actually costs. A rising neighborhood price does not automatically make a rental purchase viable.
Consider an illustrative property producing $60,000 in annual collected revenue and requiring $28,000 in annual operating expenses. Its remaining $32,000 is not all spendable profit if debt payments, replacement reserves, or further capital work still need to be funded.
Development properties add another layer. A parcel marketed with approved plans or RTI status may reduce some approval uncertainty, but the acquisition still requires construction budgeting, financing, schedule analysis, and verification of the actual permit record.
Evaluate each investment against an alternative use of your capital. The question is not merely whether the property might appreciate. It is whether its potential reward reasonably compensates you for its costs, workload, concentration, and downside.
An original example: two homes, two different markets
Imagine a buyer comparing a renovated condominium with a detached home that needs substantial repairs. Both are listed at $900,000. This is a hypothetical comparison, not a report about actual listings.
The condominium has several similar units available nearby. Its association documents reveal planned work that requires further investigation. The detached home has fewer close substitutes, but its roof and electrical system need professional estimates.
A broad county price statistic does not resolve this choice. The condominium requires analysis of building-level obligations, financing, and competing inventory. The detached home requires a larger initial repair budget and a realistic plan for completing the work.
Now imagine the condominium seller offers a closing-cost credit. That may help with upfront funds, but it does not eliminate future association expenses. Imagine the detached-home seller reduces the price. That may improve value, but it does not make the required projects easier to fund immediately.
The better decision comes from comparing the total commitment and the buyer’s capacity to manage it. The same asking price can conceal very different financial experiences.
Build a repeatable market-reading routine
Choose a consistent search area, property category, and price range. Record the same indicators at regular intervals rather than changing the sample whenever a headline becomes exciting.
Keep a short decision log. Note why a comparable sale was included, why another was excluded, and what uncertainty remains. This turns a discussion about instinct into one about evidence.
Update your financing assumptions when lender quotes change. Update your property budget when new insurance, tax, or inspection information arrives. A search can remain active while the acceptable price for a particular home changes.
Finally, define what would make you pause. Examples include an unexplained permit issue, a payment beyond your comfort level, or an ownership plan that depends on a quick resale. Clear pause points are as valuable as clear buying criteria.
Turn a market report into a useful comparison file
A small, carefully maintained comparison file can be more useful than a large collection of unrelated headlines. For each relevant property, record the asking price, current status, important condition differences, and the date you checked the information. Add completed sales when reliable information becomes available.
Keep observations separate from interpretations. “The price was reduced twice” is an observation. “The seller must be desperate” is an interpretation that may be unsupported. “Three close substitutes remain available” is an observation. “Prices will fall next month” is a forecast.
This distinction helps buyers and sellers discuss the same evidence without treating assumptions as facts. It also creates a record of how the market is changing around the specific decision.
Use ranges when the evidence is thin
A highly unusual property may not have several recent, closely comparable sales. In that situation, a narrow-looking value estimate can imply more confidence than the evidence supports.
Identify the strongest comparisons and explain their limitations. Then consider a reasonable range, the property’s unique attributes, and the choices currently available to buyers. A range is not a failure of analysis; it can be the more honest way to represent uncertainty.
For a seller, the range helps frame a pricing strategy and review point. For a buyer, it helps establish a sensible offer boundary without claiming to know the only correct price.
Decide which new information would change your position
Before acting, write down what would cause you to reconsider. A buyer might respond to a verified repair estimate, a financing change, or a new comparable sale. A seller might respond to consistent feedback and a stronger competing listing.
Not every new headline deserves a new strategy. Focus on information that changes the property’s relative value, affordability, or transaction risk.
This approach is especially useful when other people offer confident but conflicting opinions. You can ask whether the opinion is supported by relevant evidence and whether it changes an actual decision variable. The objective is not to ignore market commentary. It is to keep commentary in its proper place: context for a property-specific judgment, not a replacement for one.
Frequently asked questions about the real estate market
Can prices rise while buyers gain negotiating power?
Yes. A broad price measure can rise while particular listings face more competition or longer marketing times. Prices, transaction volume, and negotiating leverage measure different things. Review the property segment and the available alternatives instead of assuming that a rising median eliminates opportunities.
Does a listing below the neighborhood median represent a bargain?
Not necessarily. The median may include larger, renovated, or otherwise different homes. A lower-priced property may also have higher recurring costs or require substantial work. Compare similar properties and calculate the full ownership commitment before interpreting the discount.
How many comparable sales are enough?
There is no universally sufficient number. Relevance and reliability matter more than collecting a large stack of weak comparisons. A useful analysis explains why the selected homes compete with the subject property, how recent they are, and which differences require further judgment.
Should a buyer wait until the news confirms a market bottom?
A market bottom is easier to identify afterward than during a purchase decision. Waiting can improve savings or reveal better options, but it can also change available inventory and financing. A more useful approach is to define affordability, property standards, and downside tolerance before deciding to act.
Can one transaction change a neighborhood’s apparent trend?
It can, especially in a small sample. An unusually expensive or inexpensive closing can influence an average, and a shift in the types of homes sold can affect the median. Ask how many transactions support a reported trend and whether the comparison period is genuinely comparable.
Turn market information into a property-specific plan
The Los Angeles real estate market is most useful when interpreted as a set of local decisions, not a prediction to follow blindly. Match the evidence to the property, calculate the full commitment, and allow room for uncertainty.
For a buyer, that means a search grounded in payment comfort and realistic alternatives. For a seller, it means a pricing and marketing plan supported by competing inventory. For an investor, it means separating an appealing story from documented operating and development assumptions.
Contact Rana Real Estate to discuss your target area and next move, or request a home evaluation to begin a property-specific selling conversation.
This article provides general education, not individualized financial, legal, tax, insurance, or investment advice. Statistics are dated; confirm current information and consult appropriately licensed professionals before acting.
Sources and references
Sources checked October 20, 2026. Reporting periods and hypothetical examples are identified in the article.
- California Association of REALTORS: Current Sales and Price Statistics, September 2026 county table
- Freddie Mac: Primary Mortgage Market Survey, October 15, 2026
- Los Angeles Office of Finance: Real Property Transfer Tax and Measure ULA FAQ; thresholds effective July 1, 2026
- Consumer Financial Protection Bureau: Why did I receive different valuations?
- Consumer Financial Protection Bureau: How can I figure out if I can afford to buy a home?
- Consumer Financial Protection Bureau: Schedule a home inspection
- National Association of REALTORS: Consumer Guide, Marketing Your Home
- Los Angeles County Assessor: New Homeowners and Supplemental Property Taxes
- California Department of Insurance: Homeowners Insurance Comparison Tool
- Los Angeles Department of Building and Safety: Permitting, inspections, and property records